What to do with your bonus or 13th cheque
The short answer
Start with your real number. Your bonus is taxed at your highest tax rate, so less lands than the figure on your letter. Then give it a job before it arrives. Most people split it between getting through January, paying down debt, building a buffer and something they want now. There’s no single right split.
Why does your bonus feel smaller?
There’s no special bonus tax. SARS treats a bonus or 13th cheque as a once-off payment, so your employer works out your tax for the year with the bonus and without it, then takes the difference from your bonus in the month it’s paid.
Your salary has already used up the lower tax brackets, so the whole bonus is taxed at your top rate. It isn’t taxed more than your salary. It just feels that way, because all the tax comes off in one month.
Rough example
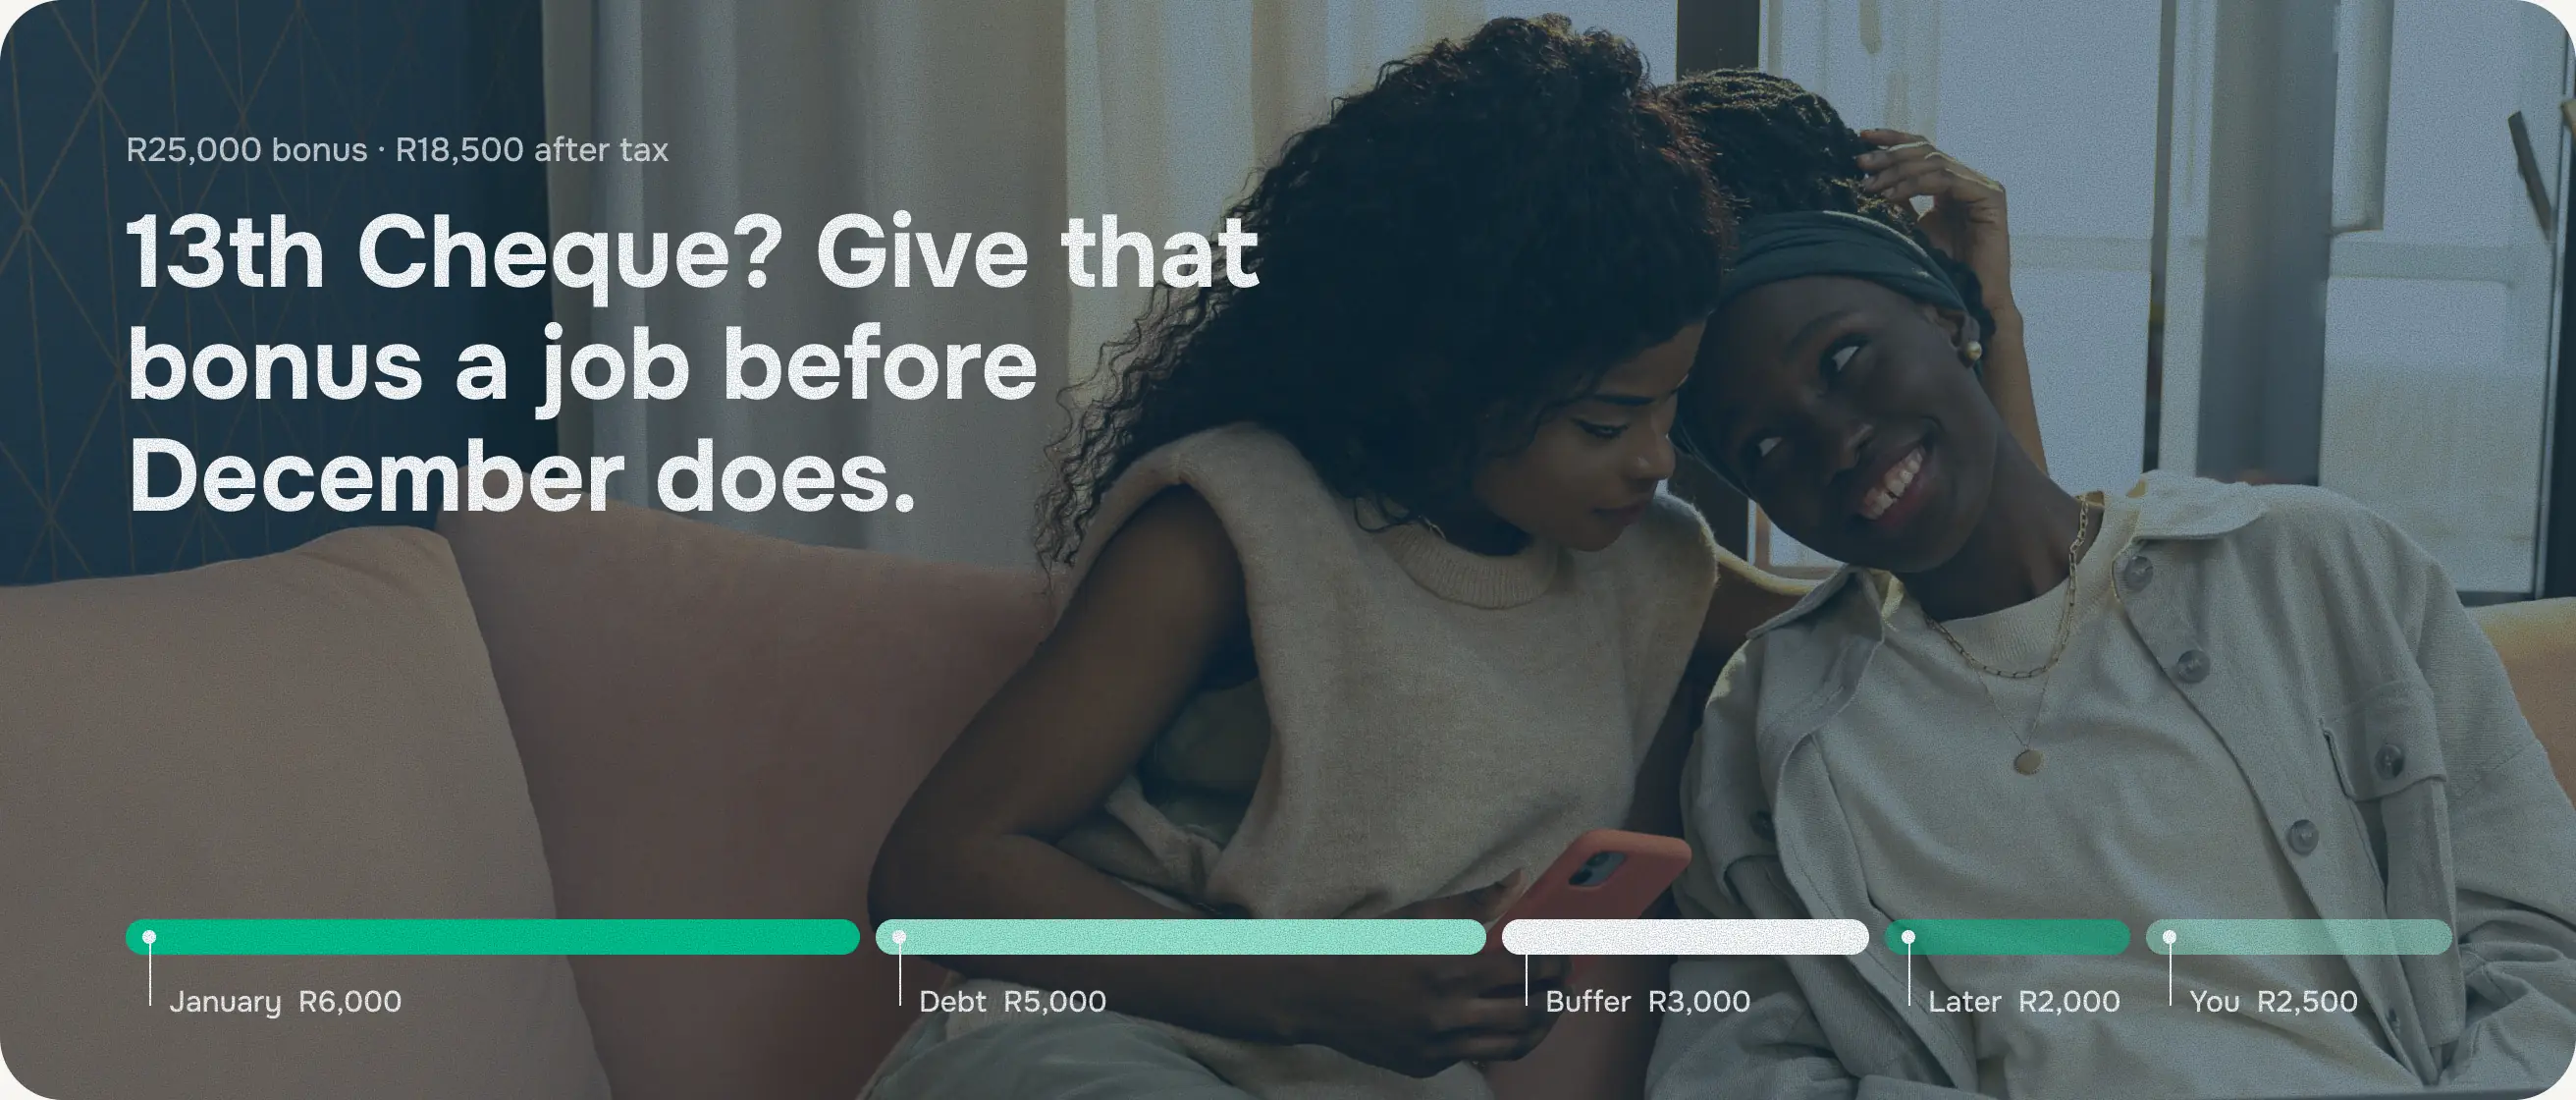
On a R25,000 monthly salary, a R25,000 bonus has about R6,500 taken off in PAYE, so about R18,500 lands. Your own number depends on your salary and deductions.
Why decide before December?
December makes decisions for you if you don’t.
Many employers pay December salaries early, so the gap to your January payday is longer than usual. Add festive spending, travel, school costs and January debit orders, and a bonus can be gone before you’ve chosen what it was for.
Giving it a job first doesn’t mean saying no to the festive season; it means having absolute clarity about what you’re saying yes to.
Five jobs a bonus can do
Get you through January. Set aside enough to cover the gap to your January payday, including the debit orders that land in between. It’s the job people most often forget.
Pay down expensive debt. A lump sum on a high-interest credit card or store account saves you that interest every month after.
Build a buffer. A few months’ essentials, kept somewhere easy to reach, turns the next surprise into an inconvenience instead of a crisis.
Put something towards later. A tax-free savings account has R46,000 of room this tax year, until 28 February 2027. Retirement annuity contributions can also reduce your taxable income, within SARS limits.
Spend some on purpose. A bonus is a reward for a year’s work. A planned treat is part of the plan, not a failure of it.
What could a split look like?
An example on a R18,500 bonus after tax:
| Job | What it covers | Amount |
|---|---|---|
| January | Debit orders and costs until your January payday | R6,000 |
| Debt | A lump sum on your highest-interest debt | R5,000 |
| Buffer | Money for surprises, kept easy to reach | R3,000 |
| Later | A tax-free savings account | R2,000 |
| You | Something you’ve been waiting for | R2,500 |
| Total | Your bonus after tax | R18,500 |
An example only, so change it to fit your own life.
What’s coming before your January payday? Add up debit orders, school costs, travel and anything you’ve already promised.
What’s costing you the most? Compare the interest on your debts with what your savings earn.
What would make next year feel different? A buffer, a smaller debt or a start on something longer term.
Where Vault22 fits, and where it doesn’t
Vault22 doesn’t pay your bonus or decide where it goes. It shows you the whole picture first: link your accounts to see your debit orders, spending and debt in one place, set a budget for December and January, and see what’s really left. Then you decide what your bonus is for.
You can start free, with budgets, goals, AI guidance and weekly account updates included. Paid plans from US$4.99 a month add daily updates, lower investment fees and accounts from more than one region.
See your December and January in one place
Start free and set a budget before your bonus lands.
Questions people ask
No. It’s taxed at your top rate, like any extra income. It feels higher because all the tax comes off in one month.
It depends on your salary. Your employer works out your tax for the year with and without the bonus, and the difference comes off your bonus.
Retirement annuity contributions are tax-deductible within SARS limits: 27.5% of your income, capped at R430,000 a year from 1 March 2026. A tax practitioner can help with your situation.
It can be a good home for money you won’t need for years. Check first that you have a buffer and aren’t paying high interest on debt.
This guide is general information to help you understand your options. It isn’t financial advice and doesn’t consider your personal circumstances.
See where you stand, in one place.
Start free, link your accounts and see what’s left for the things that matter.